When some investments grow faster than others, your portfolio can drift away from the mix you originally chose. Rebalancing means adjusting it to bring it closer to that target. It is a way to manage how much of your portfolio is in different kinds of investments—not a way to predict which investment will do best next.
This guide explains how to review your allocation and consider a rebalance. There is no single allocation or schedule that suits everyone; your target should reflect your goals, time horizon, and comfort with investment risk.
Before you start
You will need your current account statements or online account balances, a record of your target allocation, and a calculator. If your investments are spread across several accounts, gather the balances for all of them. Your allocation is usually easiest to understand by looking at the investments together, rather than treating each account as a separate portfolio.
For this guide, an allocation might be divided into broad groups such as stocks and bonds. Check what each fund actually holds: a fund name alone may not tell you whether it includes domestic stocks, international stocks, bonds, or a mix. Avoid counting the same investment twice if it appears in more than one account view.
Steps to review and rebalance
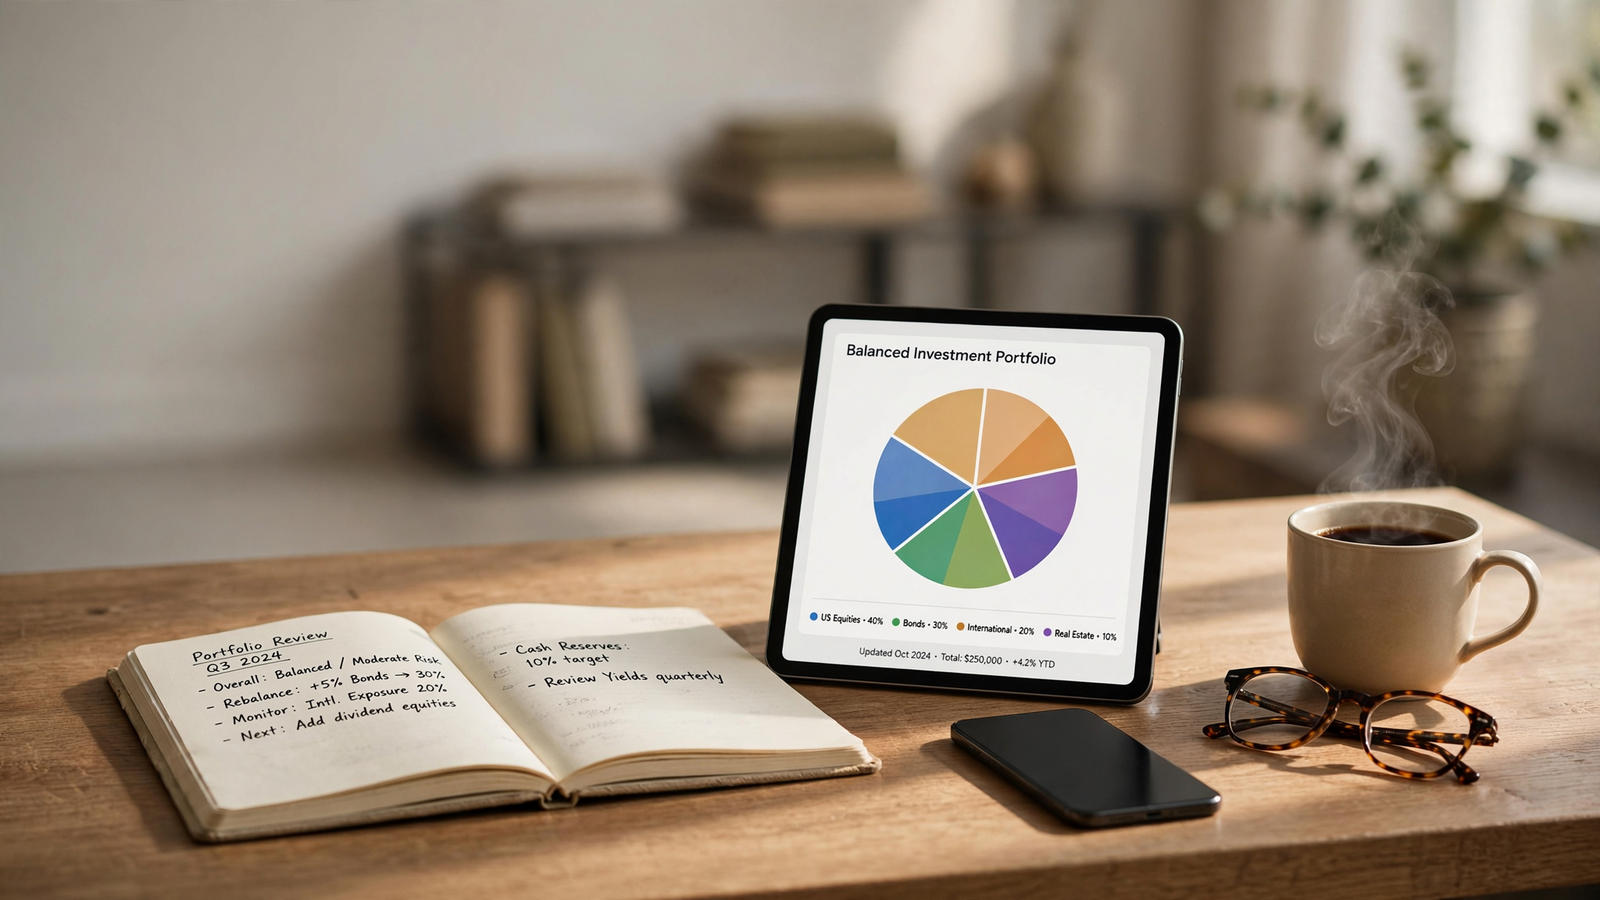
- Write down your target mix. Record the percentages you intend to hold in each investment group—for example, 60% stocks and 40% bonds. If you do not have a target, pause before trading. First consider your goals, how long the money can remain invested, and how much loss you could tolerate. A target is a plan, not a guarantee of results.
- Set a review rule. Decide in advance when you will check the portfolio. Some investors review on a regular schedule, such as every six or 12 months; others act when an investment group moves beyond a chosen range from its target. Neither method guarantees better performance. A rule can help avoid reacting to every market move.
- Find the current value of each group. Add together the values of investments in each group across the accounts you are including. If a fund holds several kinds of investments, use its published breakdown to estimate how it contributes to each group. If you cannot classify a holding confidently, check the fund provider’s materials or ask your plan administrator before making a change.
- Calculate each group’s current percentage. Divide the value of a group by the total portfolio value, then multiply by 100. For a hypothetical $10,000 portfolio with $6,800 in stocks and $3,200 in bonds, stocks make up 68% and bonds 32%.
- Compare the result with your target. If the target in that example is 60% stocks and 40% bonds, the portfolio has drifted eight percentage points above its stock target and eight below its bond target. That difference does not automatically mean you must trade; compare it with the review rule you chose.
- Consider directing new money first. If you are contributing to the portfolio, you may be able to direct new contributions toward the group that is below target. This can move the mix closer to your plan without selling an investment. Check your account’s available investment choices and contribution settings.
- If needed, make a measured adjustment. You could sell part of an overweight group and use the proceeds to buy an underweight group, or exchange investments within an account if its rules allow. In the hypothetical example, moving $800 from stocks to bonds would bring a $10,000 portfolio to $6,000 in stocks and $4,000 in bonds, assuming no market movement or transaction costs. Treat this as an illustration, not a recommended allocation.
- Check the result and record it. Review the new holdings and percentages after the trades or contribution changes are complete. Note the date, your allocation, and the reason for acting. Use the same review rule next time instead of making extra changes in response to short-term market swings.
Taxes, fees, and account rules
Where you make a change matters. Selling an investment in a regular taxable brokerage account can create a capital gain or loss, and the tax treatment can depend on the investment and how long you held it. Before selling, consider whether the possible tax bill and any trading costs make the adjustment worthwhile. IRS guidance explains that selling an investment for more than its cost can produce a capital gain.
Trades inside many tax-advantaged retirement accounts generally do not create a current capital-gains tax bill just because you exchanged one investment for another. However, account rules, fees, and taxes on withdrawals may still apply. Check the terms of your account or workplace plan; do not assume every transaction is free or permitted.
You do not need to rebalance every time the market moves. Frequent adjustments can mean more costs and, in taxable accounts, more occasions to realize gains. Rebalancing also cannot prevent losses or guarantee a particular return.
Things to know
- Keep the target in view. Rebalancing restores a chosen mix; it does not require changing that mix whenever one investment has recently performed well or poorly.
- Use a consistent method. A calendar check or a predetermined drift range can make decisions less reactive. Choose a rule you can realistically follow.
- Get help if the picture is unclear. If you are unsure how a complex fund is invested, how a sale will be taxed, or what your plan permits, check the official account and fund information or consult a qualified financial or tax professional.
A simple review can show whether your investments still match the plan you chose. Gather the full picture, compare it with your target, and consider contributions, taxes, fees, and account rules before trading. Small, deliberate checks can help you stay focused on your own long-term plan.