Buying a home can build equity and stability, but it also brings one‑time costs, taxes, upkeep and the risk that the market won’t cooperate. This guide walks you—step by step—through a simple, evidence‑based way to judge whether buying makes sense if you expect to live in a place for only a few years (three to seven years is a common test window).
What you will need
- An estimate of the purchase price for the kind of home you’d buy (or the listing you’re considering).
- Current monthly rent for a similar nearby unit.
- Your likely down payment and mortgage rate (or use today’s rates from an online mortgage calculator).
- Local property‑tax rate (or a tax estimate from county assessor), homeowners insurance quote, and any HOA fees.
- A realistic estimate for closing costs (buyer) and selling costs (seller agent commission and closing fees).
- Time horizon: how many months you expect to own before selling.
Steps
- Pick a holding period in months. Decide how long you expect to stay (for example, 36, 48 or 60 months). This is the single most important input because short horizons raise the impact of one‑time fees.
- Estimate upfront and exit (selling) costs. For buying, budget buyer closing costs of about 2%–5% of the purchase price (varies by state and loan). For sale, plan seller costs (agent commissions and transfer fees) — many sellers pay about 5%–6% in agent commissions. Add any pre‑sale repairs you’d need to make to sell. Amortize the total (buy + sell + any prep) over your holding months: total transaction costs ÷ months owned = monthly amortized transaction cost. ([myhome.freddiemac.com](https://myhome.freddiemac.com/blog/homebuying/what-are-closing-costs-and-how-much-will-i-pay?utm_source=openai))
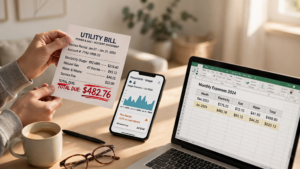
- Compute the mortgage principal & interest (P&I) payment. Use a mortgage calculator (or your lender’s Loan Estimate) to get the monthly P&I for your chosen price, down payment and interest rate. Add property tax (annual tax ÷ 12), homeowners insurance (annual ÷ 12), and any HOA fee. These together are your estimated recurring housing cost as an owner.
- Add a maintenance buffer. Set aside a maintenance estimate—industry shorthand is about 1% of the home’s value per year (divide by 12 to get a monthly figure). That covers routine upkeep and small repairs; big replacements should be treated separately. Treat the 1% rule as a rule of thumb, not a guarantee—adjust up if the home is older or has known issues. ([angi.com](https://www.angi.com/press/angis-2025-state-of-home-spending-pulse-report?utm_source=openai))
- Put the owner monthly total together. Owner monthly cost = mortgage P&I + (property tax ÷ 12) + (insurance ÷ 12) + HOA + (maintenance ÷ 12) + monthly amortized transaction cost.
- Compare to renting. Take the monthly rent for a similar place and add renter’s insurance and any expected rent growth you think likely. Remember rent can rise over time; renting gives flexibility but no equity. ([consumerfinance.gov](https://www.consumerfinance.gov/owning-a-home/prepare/consider-whether-its-the-right-time-for-you-to-buy/?utm_source=openai))
- Estimate expected home price change and equity build‑up (optional but useful). Conservatively estimate local annual home price change (use the FHFA or Case‑Shiller indices for local/metro history). Add expected principal paydown (the portion of P&I that reduces loan balance) to projected appreciation to estimate likely equity when you sell. Beware that short holding periods can leave little net equity after selling costs. Use local indices rather than national averages if you can. ([fhfa.gov](https://www.fhfa.gov/reports/house-price-index?utm_source=openai))
- Run a simple breakeven check. Subtract monthly rent from monthly owner cost. If owner cost is higher, multiply the monthly difference by your months of ownership — that’s the extra money you’d spend to own for that period (before counting any expected appreciation). Compare that figure to your projected net equity gain from appreciation + principal paydown. If the extra cost is larger than expected net equity, renting likely wins for your horizon; if not, buying may be reasonable.
- Do two sensitivity checks. Recompute the comparison with (a) a lower appreciation assumption (0% or negative), and (b) a higher maintenance or selling‑cost assumption. If your decision flips under modest changes, favor the lower‑risk option for your situation.
Tips & warnings
- Get localized numbers: property tax rates, insurance costs and rent vary a lot by neighborhood; local data matter more than national averages. ([myhome.freddiemac.com](https://myhome.freddiemac.com/blog/homebuying/what-are-closing-costs-and-how-much-will-i-pay?utm_source=openai))
- Closing costs vary by loan and state; buyers commonly pay several percent of price at closing. Save for both the down payment and closing costs before you buy. ([myhome.freddiemac.com](https://myhome.freddiemac.com/blog/homebuying/what-are-closing-costs-and-how-much-will-i-pay?utm_source=openai))
- Tax rules (like mortgage interest deductions) change and may not help you if you take the standard deduction; check the current IRS guidance or talk to a tax preparer. Don’t assume a tax break will make buying cheaper. ([irs.gov](https://www.irs.gov/publications/p936?os=vbf&ref=app&utm_source=openai))
- If you need flexibility (job changes, uncertain family plans), renting reduces the risk and cost of having to sell quickly in a down market.
- Use reputable online calculators (CFPB, Freddie Mac, Zillow, local housing authority tools) to check your math. They’ll also let you run scenarios quickly. ([consumerfinance.gov](https://www.consumerfinance.gov/owning-a-home/prepare/consider-whether-its-the-right-time-for-you-to-buy/?utm_source=openai))
Deciding whether to buy within a short time frame comes down to comparing (a) the extra monthly and one‑time costs of owning, amortized over how long you’ll keep the home, versus (b) the likely financial upside from appreciation plus forced savings through mortgage paydown. Non‑financial factors—stability, tax situations, comfort with repairs and local market liquidity—also matter. Do the numbers honestly, run sensitivity tests, and when the math is close, lean on the non‑financial priorities to decide.
With this worksheet you can turn an emotional “should I buy?” into a clear, repeatable calculation. If you’d like, tell me the city, price range and your expected down payment and I can help you run the numbers for one scenario.